Key points
- In Chapter 13, a wholly unsecured junior lien on a principal residence may be treated as unsecured.
- If value exceeds the first mortgage at all, the second lien generally cannot be stripped from a residence.
- This remedy is not available in Chapter 7, and the lien removal usually depends on completing the plan.
- Expect the lender to challenge comparables, condition, and timing; the report should anticipate that.
- Inspected reports are usually the safer choice for contested motions.
- This page is general information from an appraiser, not legal advice. Brian Ward is not a lawyer, and nothing here creates an attorney-client relationship; ask a bankruptcy attorney how the law applies to your case.
The basic idea
When a home has more than one loan against it, each lender's claim is secured only to the extent there is value in the property to support it. Bankruptcy law values secured claims by looking at the collateral. If the home is worth less than what is owed on the first mortgage, a second mortgage or home equity line of credit has no equity at all behind it. In a Chapter 13 case, courts in the Ninth Circuit, which includes California, have allowed a wholly unsecured junior lien on a debtor's principal residence to be treated as an unsecured claim. The lien is then removed when the debtor completes the plan and receives a discharge. Your attorney decides whether the facts support this and files the motion. The appraisal is the evidence of value.
All or nothing
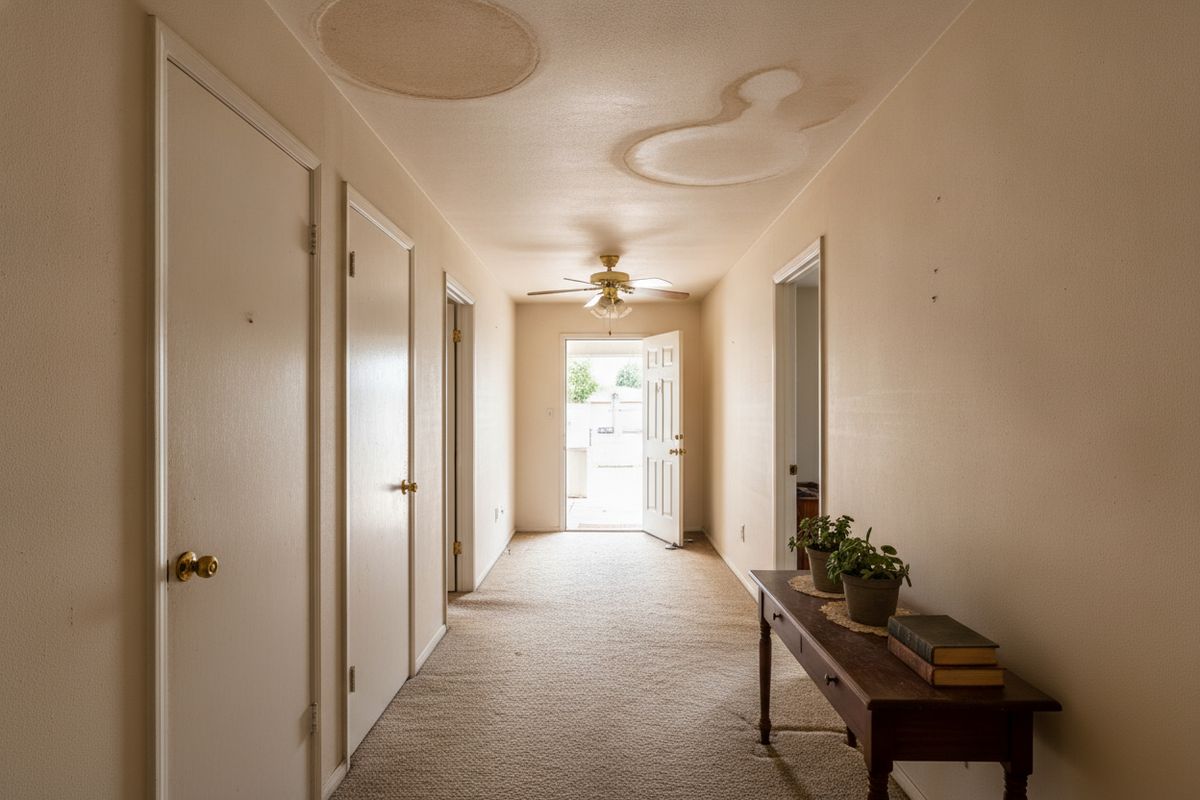
The rule for a principal residence turns on a narrow point: the junior lien must be entirely unsecured. If the home's value exceeds the first mortgage balance by even a modest amount, the second lien is at least partly secured, and the protection for home loans generally prevents it from being stripped. That makes the margin between value and the senior balance the whole question. A report that is careless, relies on stale sales, or ignores obvious features can be picked apart by the lender's appraiser. Brian approaches these assignments expecting that a second appraiser will review the comparables and adjustments line by line. Every choice in the report is explained, and condition issues are supported with photographs rather than general statements.
Chapter 13 only, and the plan has to finish
This remedy belongs to Chapter 13. The U.S. Supreme Court has held that a Chapter 7 debtor cannot use bankruptcy valuation to void a wholly underwater junior mortgage, so homeowners in Chapter 7 should not expect this result. In Chapter 13, the lien is not erased the day the motion is granted. The order usually takes effect when the plan is completed and the discharge is entered. If the case is dismissed or converted before then, the lien may survive. These timing and eligibility rules are legal matters for your attorney, and this page simplifies them. What matters for the appraisal is that the report reflects the value as of the date your attorney specifies and clearly identifies that date.
What lenders tend to challenge
A junior lender opposing a motion to value often focuses on a few areas. First, comparable selection: were the sales truly similar in size, age, quality, and location, and were better matches ignored? Second, condition: is the claimed damage real, and was it priced reasonably? Third, timing: were sales from a weaker or stronger period used without a time adjustment? Fourth, the first mortgage figure itself, which comes from the debtor's records and the lender's statements, not from the appraiser. Brian addresses the first three directly in the report and includes a broad set of comparable sales so the reasoning can be tested. He does not shade a value to reach a target, because a report built to hit a number tends to fail exactly when it is challenged.
Inspected reports are usually the right tool
Since a motion to strip a lien may be challenged, the $699 inspected Standard report is usually the right fit for a single-family home or condo. Interior photos documenting condition, measurements confirming size, and a clear sketch give the court something concrete. A Desktop report may serve when the gap between value and the first mortgage is very large and opposition is unlikely, but your attorney should make that call. If the lender orders its own appraisal and the case heads toward an evidentiary hearing, Brian can review the opposing report with your attorney and, if needed, testify. Time for depositions and testimony is charged apart from the appraisal and agreed on beforehand. Brian will discuss these options frankly when you call.
Cramdown on other property
The strict all-or-nothing rule applies to the debtor's principal residence. Rental houses, duplexes, second homes, and vacant land can be treated differently in Chapter 13, and a secured claim on such property may sometimes be reduced to the property's value, with the rest treated as unsecured. Your attorney will explain whether that is available. For those properties, Brian considers the features that drive investment value, such as unit mix, rent levels in the area, and deferred maintenance in each unit. Call (760) 557-2147 with the property address, the effective date your attorney needs, and the loan positions involved, and you will receive a written quote before any work begins. Fees are due on delivery, and firms can be invoiced. Have your loan statements handy.